What every Henrico homeowner should check before hiring a storm damage pro
Before you sign anything after a Henrico storm, check these seven things - license, insurance, written scope, pricing, and the red flags that stall claims.
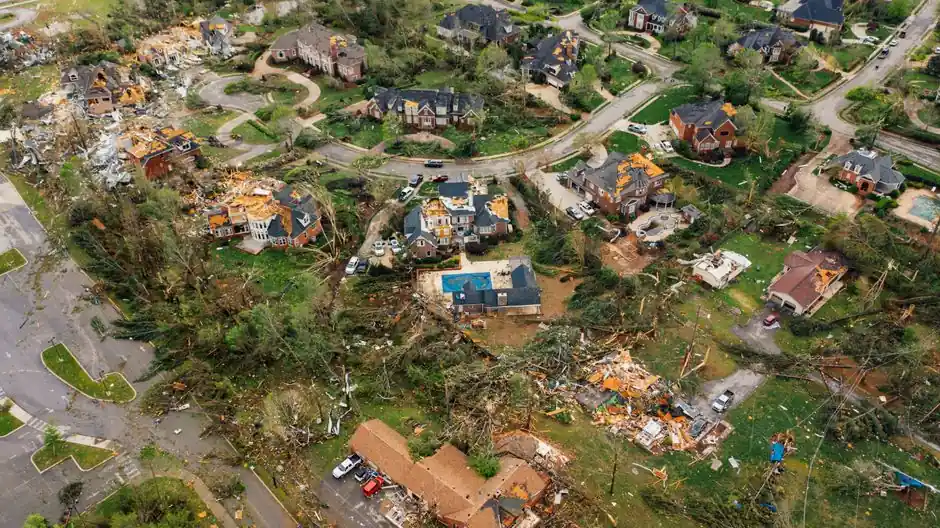
Before you hire a storm damage pro in Henrico, check seven things: a valid Virginia contractor license through DPOR, general liability and workers' comp coverage, a written scope of work, a clear insurance-claim process, itemized pricing, local references you can call, and a signed contract before any work starts. Skip any one of those and you are the one holding the risk, not the contractor.
We run storm calls across Henrico every week, from Tuckahoe to Varina, and the homeowners who get burned almost always skipped the same two or three checks. Here is the full list, in the order we would run it ourselves.
Check the Virginia contractor license and DPOR record first
Virginia does not license "storm chasers" as a category, but it does license contractors, and any crew doing structural, roofing, or water-mitigation work on your house needs a valid Virginia contractor license on file with the Department of Professional and Occupational Regulation. You can pull that record yourself in about four minutes at dpor.virginia.gov.
Look for three things on the DPOR page: an active status, a class that matches the job size (Class C covers jobs under $10,000; Class B covers $10,000 to $120,000; Class A covers anything above that), and a complaint history you can actually read. If the license shows as expired or the class does not match the scope, stop there. A Class C roofer cannot legally take a $40,000 rebuild in Henrico, no matter what the estimate says.
Ask for the license number in writing. A legitimate contractor hands it over without a pause. The ones who say "we're licensed in Virginia, don't worry about it" are the ones you worry about.
Verify general liability and workers' comp before anyone climbs your roof
General liability insurance protects your house if a worker drops a bundle of shingles through your ceiling. Workers' compensation protects you if a worker falls off your roof. Those are two different policies, and you want proof of both before anyone sets a ladder against your siding.
Ask for a certificate of insurance (COI) with your address listed as the job site, then call the insurance carrier's number on the certificate to confirm the policy is active. We have seen homeowners handed COIs that expired eight months earlier. The phone call takes two minutes and it is the single best protection you have against a lien on your property.
If a crew shows up with no COI and no workers' comp, you are the general contractor of record. That means an injured worker can file against your homeowner's policy, and your rates go up whether or not the work was any good.
Get a written scope of work, not a number on a business card
A written scope of work is the document that decides whether your claim gets paid in full or gets nickel-and-dimed for six months. It should list every affected material by name and quantity - 42 squares of architectural shingles, 180 linear feet of 6-inch K-style gutter, 14 sheets of 1/2-inch drywall - not "roof repair" and "miscellaneous."
In Henrico, the scope matters more than in a lot of places because the housing stock is so mixed. A 1950s brick ranch in Lakeside and a 2016 build in Short Pump take completely different repair approaches after the same hailstorm. A contractor who writes one generic scope for both has not looked at your house.
Ask these questions before you sign:
- What is the exact scope, line by line, with quantities?
- What is excluded - and why?
- How long will the work take, start to finish?
- Who is the on-site supervisor, and what is their direct number?
- What is the payment schedule, and how much is due up front?
On that last point: Virginia's Board for Contractors expects a down payment that is reasonable relative to the job. Ten to thirty percent up front is normal. Fifty percent before materials land is not.
If you are dealing with water inside the house, not just damage outside, the scope needs to include drying equipment, moisture readings, and a documented dry standard. That is a different trade than roofing, and it is worth reading how water damage restoration company Henrico Virginia handles the drying side before you assume your roofer covers it.
Ask how they handle the insurance claim
Most Henrico storm claims run through a homeowner's policy, and the contractor's role in that process is the difference between a clean settlement and a fight. Ask up front: does the contractor document the damage with photos and moisture readings, do they meet your adjuster on site, and do they bill the carrier directly or expect you to front the money?
A contractor who meets the adjuster on site catches the line items adjusters miss - drip edge, ice-and-water shield, code-required upgrades under the 2021 Virginia Uniform Statewide Building Code. Those add up fast. On a typical Henrico roof claim, missed code items run $1,200 to $3,800.
You also want to know who negotiates if the carrier underpays. Some contractors walk away when the first offer is low. Others, like the team behind our storm damage claim help Henrico service, will re-document and push back with a supplement. Get that answer in writing before work begins.
One more thing: never sign a document that assigns your claim rights to a contractor. Virginia law allows it in narrow cases, but it hands control of your policy to someone else. Pay the contractor; keep the claim in your name.
What should a storm damage restoration contractor in Henrico actually charge?
Typical 2026 pricing in the Henrico area runs $450 to $900 for emergency board-up and tarping on a single-family home, $1,800 to $4,500 for a full roof replacement on a 2,000-square-foot house using architectural shingles, and $2,500 to $7,000 for water extraction and structural drying on a flooded basement, depending on square footage and how long the water sat.
Those numbers move based on four things: roof pitch and stories, how much debris has to come off before new material goes on, whether the job needs permits from Henrico County, and whether you are filing a claim or paying out of pocket. A steep 12/12 pitch on a two-story colonial in Glen Allen costs more to work on than a low-slope ranch in Sandston, and any honest estimate reflects that.
Be skeptical of any number that lands more than 30 percent below the others. In this trade, a lowball estimate usually means a thinner underlayment, a crew paid by the square with no supervision, or a scope that quietly drops the code-required items your adjuster already approved.
How do I verify a storm damage restoration contractor in Henrico Virginia?
Pull the license on DPOR, call the insurance carrier on the COI, check the business address on Google Maps, and ask for three local references from jobs completed in the last 12 months. Those four steps take about 20 minutes and eliminate most of the risk.
The reference calls matter more than the online reviews. Ask each reference three questions: did the crew show up when they said they would, did the final invoice match the estimate, and would you hire them again. If two of three references hesitate on any of those, keep looking.
You can also check the Henrico County permit portal to see whether a contractor has pulled permits under their own license or under someone else's. A crew that consistently works under another company's permit is a crew you do not want on your roof.
Red flags that should end the conversation
Some warning signs are obvious, others are not. Here is what we tell neighbors to walk away from.
- Door-to-door solicitation right after a storm. Legitimate local crews are booked out for days after a major event. Out-of-state crews that appear within 24 hours and knock on every door on the street are usually gone within a week.
- No physical address, or a P.O. box only. You need a place to send a certified letter if something goes wrong.
- Pressure to sign today for a "storm discount." Real pricing does not expire in four hours.
- Cash-only payment, or a request to make the check out to an individual. Both are how you lose your recourse.
- An offer to "waive your deductible." That is insurance fraud in Virginia, and it puts your claim at risk.
- No written contract, or a contract with blank line items. If the scope is not filled in, you are signing an open invoice.
One more: a contractor who tells you not to call your insurance company first. You always call your carrier first. Anyone who wants to get between you and your adjuster is managing their own interests, not yours.
When to call a professional
Call a professional when water is still moving, when the damage involves structure, or when you cannot safely get on the roof to see what happened. Those three conditions cover most of the storm calls we run in Henrico.
Specifically, call us if you see any of the following: water staining on a ceiling that grows over 24 hours, a sagging section of drywall, shingles in the yard after a wind event, hail dents on gutters or downspouts, a crack in the foundation wider than a credit card, or a musty smell that appeared within three days of a storm. That last one usually means mold has already started, and it moves faster than most homeowners expect - visible growth can start in 24 to 48 hours in a humid Henrico summer.
Our team at BlueRidge Storm Response handles the full sequence: emergency tarping, water extraction, structural drying, repairs, and the insurance paperwork that ties it together. We work across the county, including the older neighborhoods where Storm Damage Restoration Henrico calls tend to involve both roof damage and interior water intrusion from the same storm.
If you are not sure whether the damage is serious enough to file a claim, call us anyway. A 15-minute walkthrough is cheaper than a repair you did not need or a claim you filed too late.
Frequently Asked Questions
What should I check before hiring a storm damage restoration company in Henrico?
Check four things: an active Virginia contractor license on DPOR, a certificate of insurance for both general liability and workers' comp, a written scope of work with itemized quantities, and three local references from the past 12 months. Those four checks take about 20 minutes and prevent most storm-repair problems.
How do I verify a storm damage restoration contractor in Henrico Virginia?
Go to dpor.virginia.gov and search the license number, then call the insurance carrier listed on the COI to confirm the policy is active. Cross-check the business address on Google Maps and ask for local references. A legitimate Henrico contractor will hand over all of that without hesitation.
Are storm damage restoration companies licensed in Henrico?
Yes. Any contractor performing structural, roofing, or water-mitigation work in Henrico must hold a valid Virginia contractor license through DPOR, classified as C, B, or A depending on job value. Unlicensed crews are working illegally, and you have no recourse if the work fails or someone gets hurt.
How much should I pay up front for storm damage restoration in Henrico?
Ten to thirty percent down is normal for a Henrico storm job. Anything above 50 percent before materials arrive is a red flag. Never pay in cash, never make a check out to an individual, and never sign a contract with blank line items - the scope should be fully filled in before you sign.
Can a storm damage contractor waive my insurance deductible in Virginia?
No. Waiving a deductible is insurance fraud under Virginia law, and it puts your entire claim at risk. Any contractor who offers to "eat the deductible" or "cover it with a discount" is asking you to commit fraud. Pay your deductible; let the contractor document the rest of the claim properly.
Get help with Storm Damage Restoration in Henrico
If a storm just hit your house and you need someone to look at it today, call us. We will walk the property, document what we find, and give you a straight answer on whether it is a repair, a claim, or both.
Call BlueRidge Storm Response at (804) 375-6073 for Storm Damage Restoration in Henrico, Virginia - same-day response across the county.